✦ In God We Trust · We build our future together ✦
🛡️ Free coverage check

Your policy, explained by a person, not a portal.

Send us your declarations page and an agent will call you back within one hour during business hours to walk you through it.

Free. No obligation. English · Español · Русский

📄 Send us your policy – we'll check your coverage

A photo of the first page (declarations page) is enough.

A family enjoying a picnic in the park

Where your current policy could leave you exposed

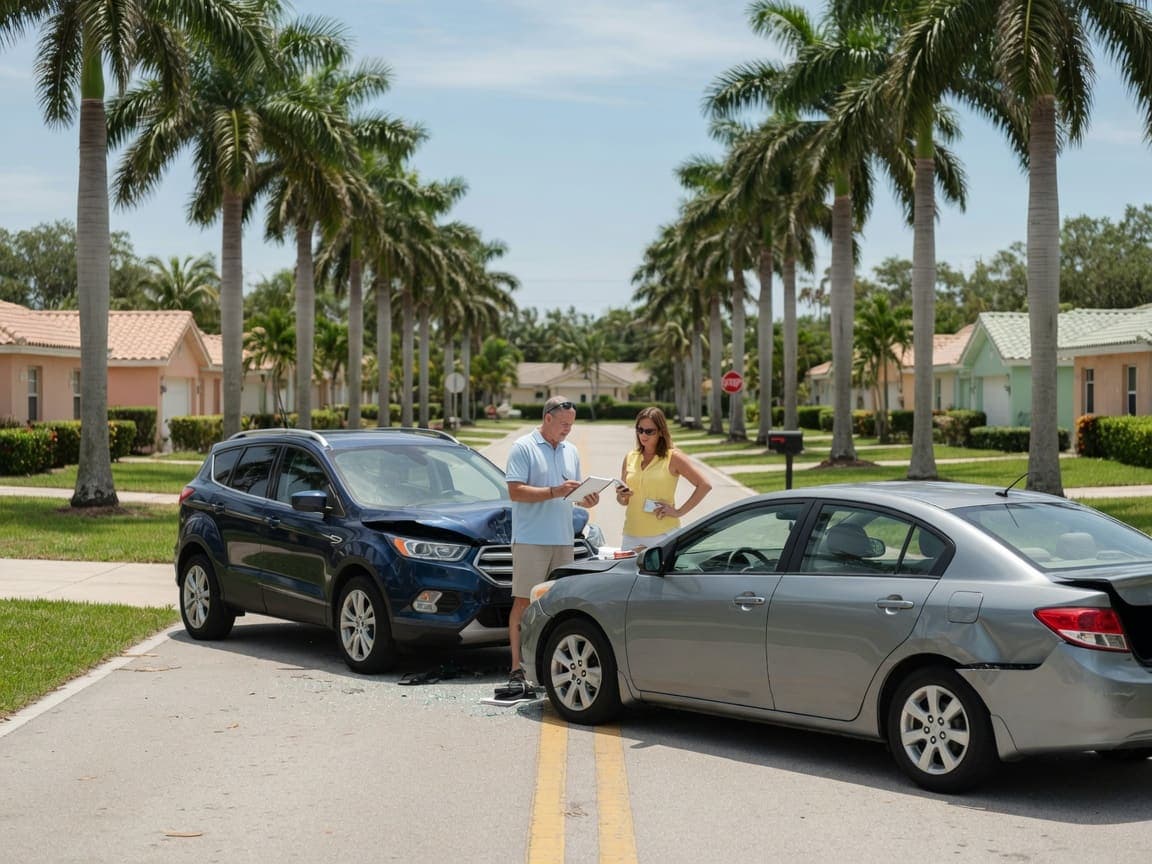
Two cars after a collision on a Florida street
Auto

Auto: the other driver's minimum policy won't cover you

Florida doesn't require most drivers to carry bodily injury liability. Your required PIP pays 80% of your medical bills, up to $10,000. If an uninsured or underinsured driver hits you and your bills go past that, Uninsured Motorist (UM/UIM) coverage is what pays the rest. Many people declined it when they bought their policy and don't know it.
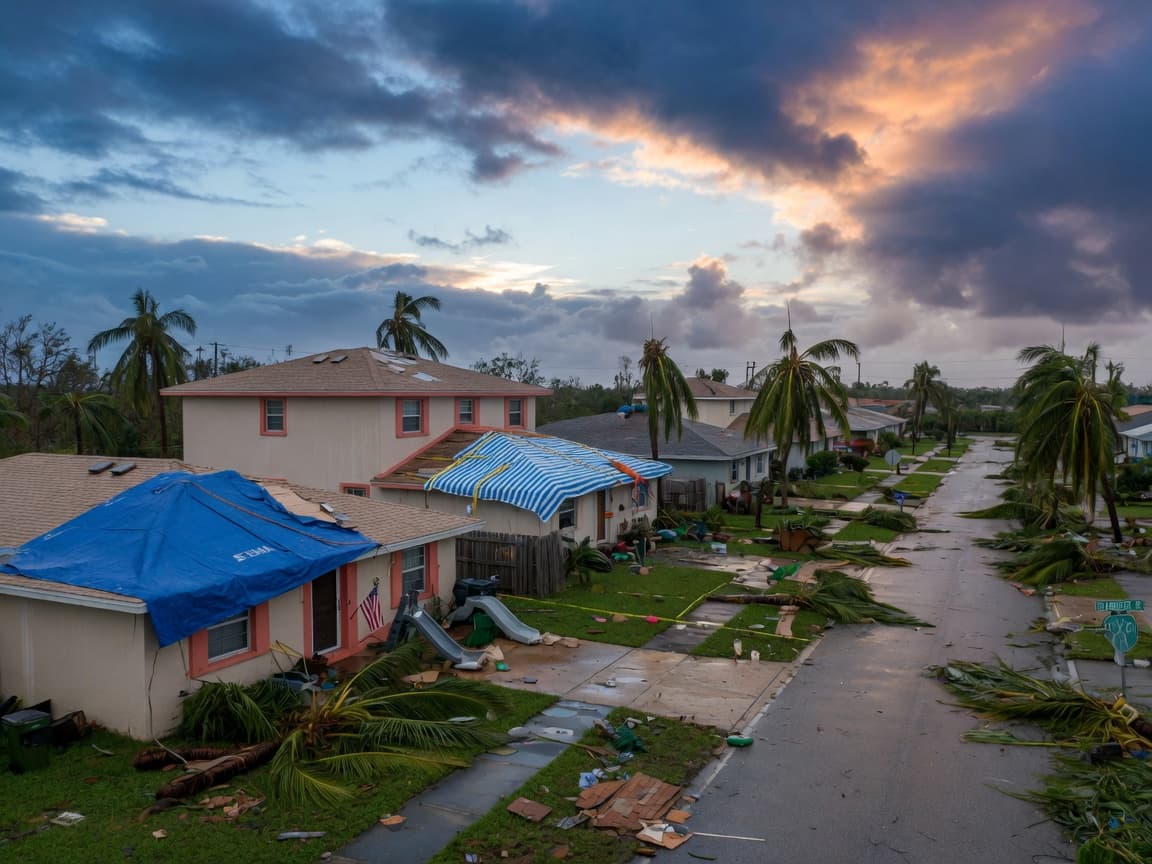
Florida homes with tarped roofs after a hurricane
Home

Home: your hurricane deductible may be bigger than you think

In Florida, hurricane deductibles are often a percentage of your home's insured value, commonly 2%, 5% or 10%, not a flat amount. On a home insured for $300,000, a 5% deductible means you pay the first $15,000 of hurricane damage yourself. We'll show you what yours is and what your options are before the next storm.

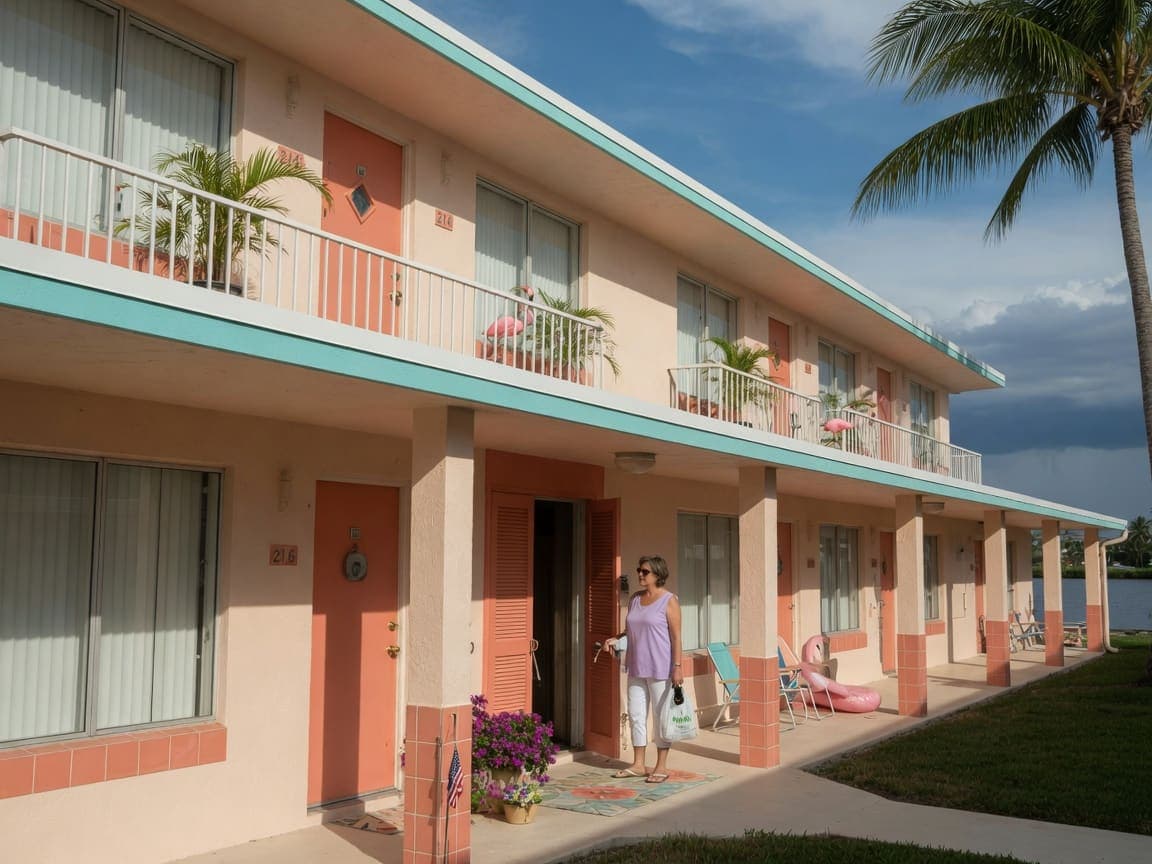
A Florida condo building
Condo

Condo: the master policy stops short of your unit

Your association's master policy covers the building. In Florida it generally doesn't cover your floors, cabinets, countertops, appliances, wall coverings, or anything you own. And when the association passes a hurricane deductible on to owners, Florida HO-6 policies are only required to include $2,000 of loss assessment coverage.

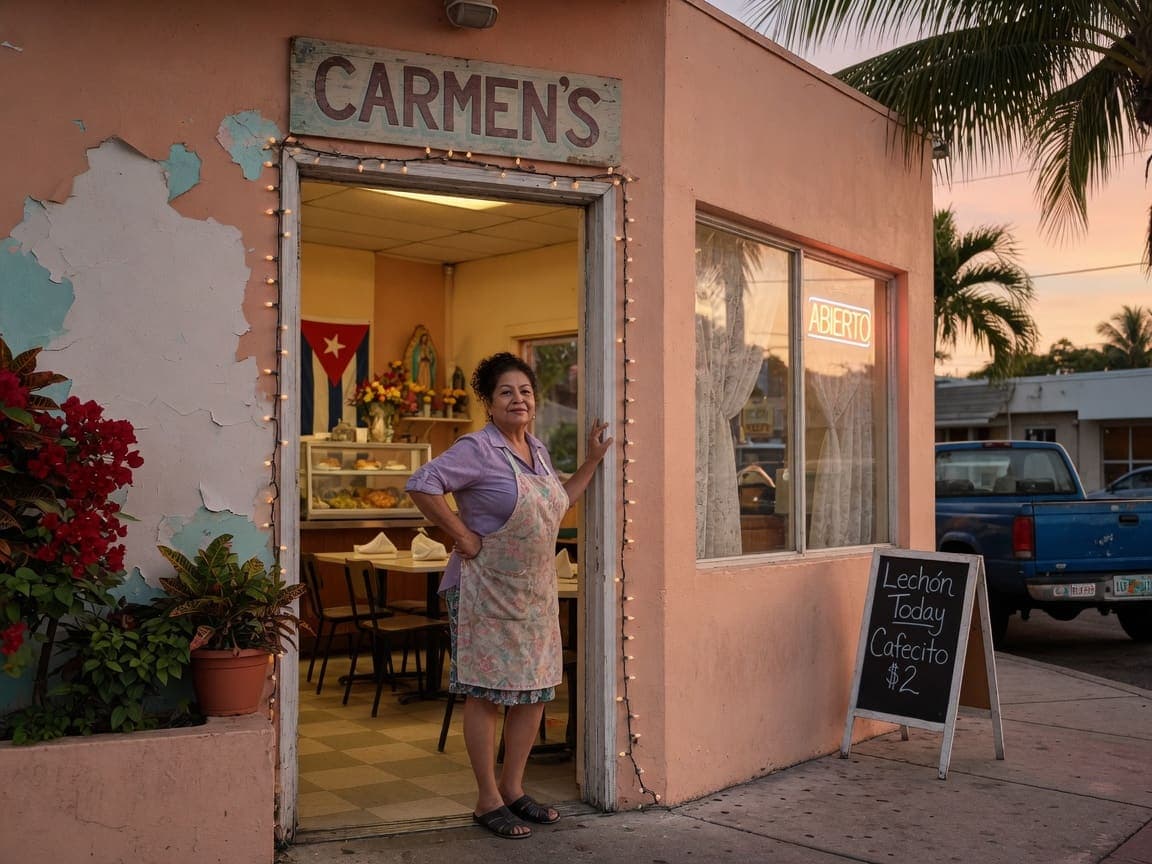
A small business owner at her shop door
Business

Business: one lawsuit can outrun your limit

A customer slips in your shop. Your work truck rear-ends someone. Many small businesses carry a $1,000,000 limit and assume that's enough. If a judgment goes higher, or the claim falls outside what your policy covers, the difference comes out of your business.

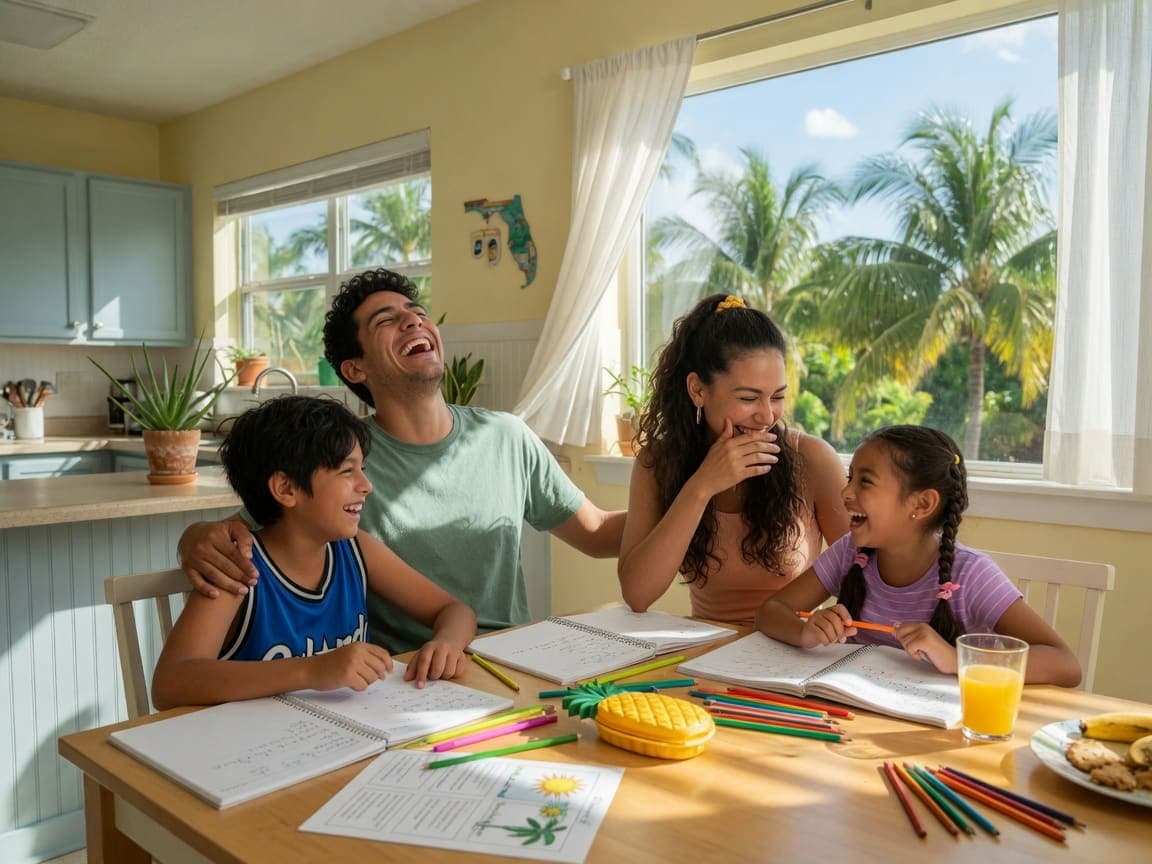
A parent with three children at the kitchen table
Life

Life: your paycheck stops, your mortgage doesn't

Picture a parent earning $60,000 a year, with a $250,000 mortgage and two kids. A work policy equal to one year's salary pays $60,000. How long could your family keep the house on that?

How it works

  1. Step 1

    Leave your number. Your name, your phone, and which policy you want checked. It takes 30 seconds.

  2. Step 2

    An agent calls you within one hour during business hours (Mon–Fri, 9 AM–6 PM ET).

  3. Step 3

    You get a clear review: what's protected, what isn't, and what to fix. You don't have to buy anything.

📄 Tip: Have the first page of your policy (the declarations page) handy. A photo on your phone is fine.

A family agency that stays after the sale

  • Family-owned agency with 5,000+ clients across Florida and a team of 12.
  • We speak English, Spanish, and Russian.
  • When you have a claim, we help you from the first call to the final payment. We don't disappear after the sale.
  • A personal agent you know by name, not an 800-number queue.
  • Licensed in Florida, license #L109526. Office: 33550 S Dixie Hwy, Suite 102, Florida City, FL 33034.

Questions people ask before a coverage check

Is it really free?

Yes. There's no fee, no obligation, and no pressure. We review what you have and tell you what we find.

Do I have to cancel my current policy?

No. Keep your policy. If we find a gap, we'll show you how to close it. If a change makes sense, we'll explain why, and the decision is yours.

Will you help me with a claim?

Yes. We help you report it, follow up with the adjuster, and keep you updated until it's settled.

My English isn't strong. Is that a problem?

Not at all. Our agents speak Spanish and Russian. Pick your language in the form and an agent who speaks it will call you.

How fast will you call me?

Within one hour during business hours, Monday to Friday, 9 AM–6 PM ET. If you write to us after hours, we call the next business morning.

What if my coverage is fine?

Then you'll know for sure, and it cost you nothing. That's a good outcome too.

Find out what your policy doesn't cover before you need it

5 minutes on the phone. Free. No obligation.

📞 (305) 859-3953

📄 Send us your policy – we'll check your coverage

A photo of the first page (declarations page) is enough.

Preferred language

Prefer to talk now? Call (305) 859-3953 or .

What our clients say

Google reviews from our clients will appear here soon.