
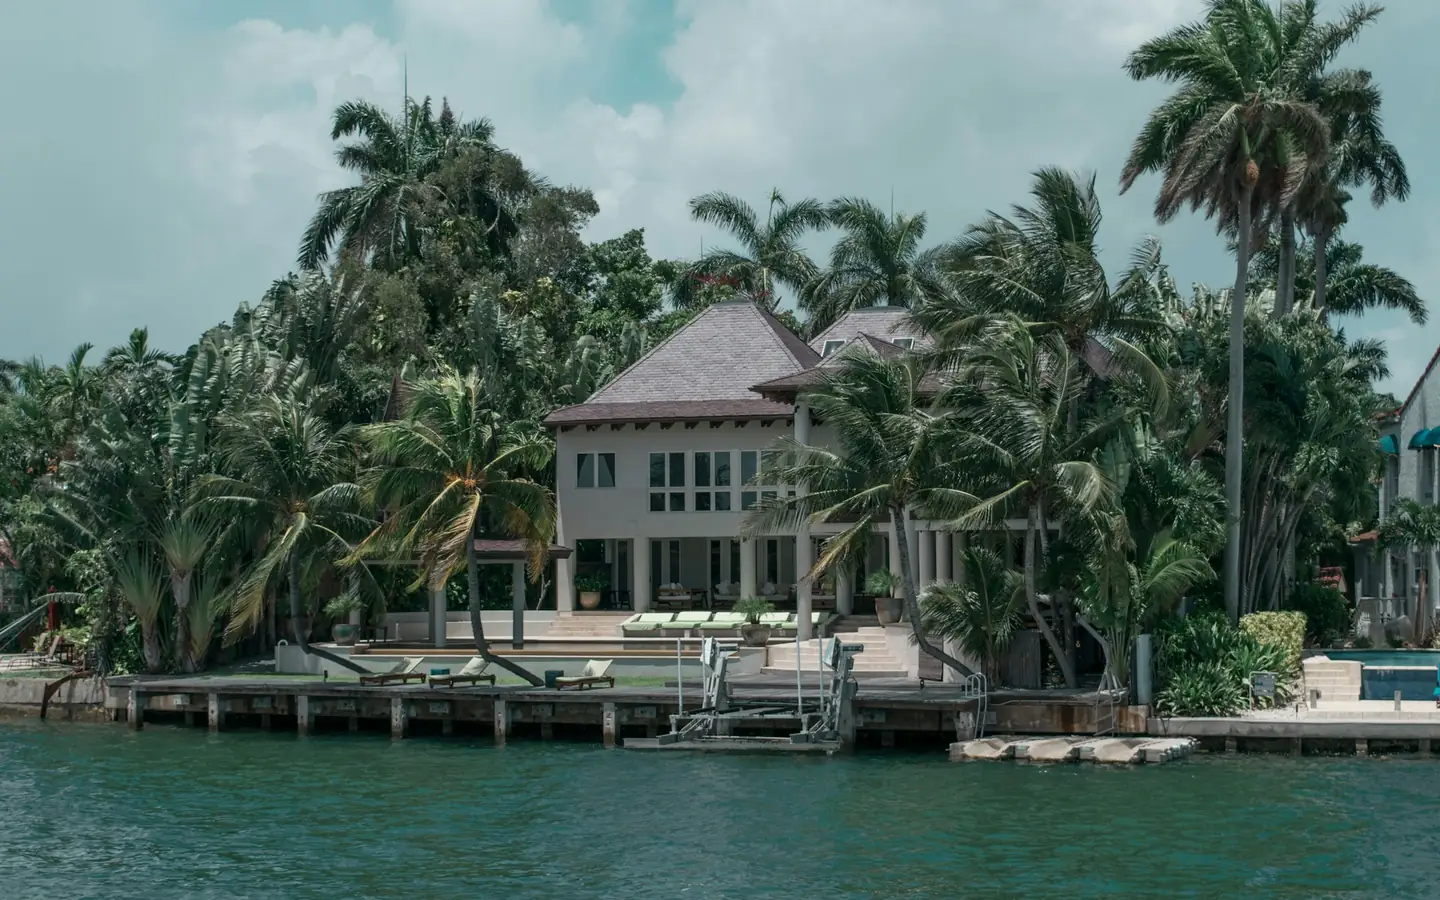
Home and condo insurance in Hollywood, a city of 1960s houses on a 2024 flood map.
Detached houses are the largest share of the housing. The beach, the lakes and the canals are why the flood map changed. We read the policy against the building you actually own. English, Spanish or Russian.
Talk to a licensed agent
Takes 30 seconds. A real agent calls you back fast.
Hollywood is a house city that also has a beach
The 2020–2024 Census estimates count about 72,800 housing units in Hollywood. About 43% are detached houses. Buildings of 50 or more units are about 19%, and buildings of 10 or more are about 38%. That is the reverse of the condo coast just south of here. In Hallandale Beach, most units are in large buildings and detached houses are a small share. In Hollywood the single-family house is the main policy, and the tower is the exception that still needs its own form.
The median year built is 1969. The 1960s are the largest decade, about a quarter of the stock, followed by the 1950s and the 1970s. More than half the units were built before 1970, and about three in four before 1980. Only about 10% date from 2000 or later. Of the occupied homes, about 59% are owner-occupied. About 6,900 units, roughly 10% of the stock, were vacant for seasonal or occasional use. A 1960s house on a canal and a winter condo on the barrier island are both Hollywood, and they are not the same insurance form.
Joseph Young’s 1920s plan put man-made lakes along both sides of Hollywood Boulevard, with an end of each lake opening toward the Intracoastal. The city still sits between the Atlantic, those lakes, a grid of canals, and the mangrove shore at West Lake. The beach is the picture. The flood problem is older and wider than the picture.
What we check in Hollywood
- The July 31, 2024 flood map for this address, not a zone letter from the 2014 Broward panels or from a Miami-Dade city.
- A house policy versus an HO-6. The house includes the roof. The condo unit does not include the building.
- Roof age and a wind-mitigation report on houses and townhomes. The form is not the milestone inspection.
- Law-and-ordinance coverage where a repair has to meet today’s elevation or opening-protection rules.
- Master-policy exclusions for condo owners: floors, cabinets, appliances, the water heater, fixtures and belongings.
- Loss assessment above the $2,000 minimum, measured against the association’s hurricane deductible.
- Milestone and reserve assessments, which are often not a covered loss.
- Seasonal and vacant-unit conditions. Check how long the place can sit empty and whether the water must be off.
- Flood as its own policy. No homeowners form and no HO-6 covers surge or rising water.
More than 11,000 properties changed flood zones in 2024
FEMA’s revised Flood Insurance Rate Maps for Broward County became effective on July 31, 2024. They replaced the maps dated August 18, 2014. Hollywood’s community redevelopment agency reports two numbers from that switch. More than 11,000 properties in the city were brought into the Special Flood Hazard Area. Another 2,115 left the mandatory-purchase requirement. A lender uses the map in effect now. A zone letter on a 2023 declaration can be describing a map that is no longer the map. Being one of the 2,115 does not mean the lot cannot flood. The city still recommends flood coverage for properties that left the mandate.
None of that map work puts flood into a homeowners or condo policy. Flood, including storm surge from the beach and rising water from the lakes and canals, is excluded. An NFIP policy generally has a 30-day wait and caps of $250,000 on the building and $100,000 on contents. For new construction and for substantial improvement, which the city describes as work above 50% of the building’s value, the Florida Building Code requires the finished floor at the base flood elevation plus one foot in the Special Flood Hazard Area. That is a building rule. It is not a coverage grant. The city’s history already has a surge date: on September 18, 1926, a hurricane hit Hollywood with wind and floodwater and killed 37 people. Wilma in 2005 is the wind benchmark for this coast, not a substitute for a flood policy.
A 1969 roof, and the towers that are not the whole city
For houses, policies issued or renewed since July 1, 2022 cannot be refused only because the roof is under 15 years old. An older roof with an inspection showing at least five years of remaining life cannot be refused on age alone. With a median year of 1969, a lot of Hollywood roofs are past both of those conversations and need the inspection, not a guess. Hurricane deductibles are $500 or 2%, 5% or 10% of the dwelling limit, once per calendar year. New claim notice is generally one year from the date of loss, landfall for a hurricane, and 18 months for a supplemental claim. Broward is in the High-Velocity Hurricane Zone, and the Broward County Board of Rules and Appeals administers that code locally. A wind-mitigation inspection on form OIR-B1-1802 is what insurers use for opening protection, roof shape and roof-to-wall connections on a house or townhome. Insurers must give the credits the statute requires when the inspection supports them. Eligible houses may use My Safe Florida Home for an inspection and, if the program’s rules fit, a grant.
The other fifth of the stock, the units in buildings of 50 or more, is a condo conversation. A residential condo or co-op of three or more habitable stories needs a milestone inspection at 30 years, or at 25 if the local building official set the earlier age, and every 10 years after that, plus a structural integrity reserve study at least every 10 years. Buildings from the 1960s and 1970s are inside that schedule. The certificate of occupancy starts the clock. The result can be a special assessment. Loss-assessment coverage under s. 627.714, at least $2,000, is for assessments tied to a covered property loss, and sometimes the association deductible, depending on the form. It is not a fund for catch-up reserves. Section 718.111(11) still leaves the interior to the unit owner: finishes, fixtures, appliances, water heaters, cabinets and personal property. That is the HO-6. A wind-mitigation form is not how a high-rise unit is usually rated, and a unit in a tower is outside My Safe Florida Home. Send the assessment notice with the policy before treating a reserve bill as a covered loss.
M&K Agency is family-owned, with a team of 12 and more than 5,000 clients across Florida. Send us your policy and we’ll check your coverage. We will say whether the gap is the roof, the flood map or the condo form, and we will not call an assessment covered until the form says so.
Serving Hollywood from Florida City
We do not have an office in Hollywood. The office is at 33550 S Dixie Hwy, Suite 102, Florida City, FL 33034, about 54 miles and about 70 minutes in light traffic via the Turnpike, I-95 and Hollywood Boulevard. Send the declarations, the flood policy if you have one, and the association certificate by WhatsApp, text or email. A visit is by appointment.
Hours are Monday to Friday, 9 to 6, and Saturday by appointment. Call (305) 859-3953 or WhatsApp (971) 998-7313. An agent calls back within an hour during business hours.
33550 S Dixie Hwy, Suite 102
Florida City, FL 33034
English · Español · По-русски
Home and condo insurance in Hollywood: common questions
The 2024 flood maps added my house to a flood zone. Did my homeowners policy pick that up?
No. The new Broward maps changed what a lender and a flood insurer use. They did not add flood or surge to a homeowners or HO-6 policy. If the city counts your property among the more than 11,000 brought into the Special Flood Hazard Area, the flood policy is the one to buy or reread. If you are among the 2,115 who left the mandate, flood coverage is still worth checking. The lot can flood without being in the mandate.
The house is from the 1960s. Can the insurer refuse it because of the roof?
Not only because the roof is under 15 years old, on policies issued or renewed since July 1, 2022. An older roof with an inspection showing at least five years of life left cannot be refused on age alone. Many Hollywood roofs are older than that. Send the declarations and, if you have it, the roof inspection. We will not guess the remaining life from the year the house was built.
We close the house in summer. Does the policy care?
Yes, if the form limits how long the house can sit empty or requires the water to be shut off. Those terms are not the same on every policy. About 6,900 units in the city were already vacant for seasonal use in the Census estimates. Check your form, or send the declarations and we will find the clause.
I own a unit in a tower, not a house. Is this the wrong page?
The flood map is the same 2024 Broward map. The form is different. You need the HO-6 against the master policy, loss assessment, and a reading of any milestone or reserve notice. About 19% of Hollywood’s units are in buildings of 50 or more, so the tower is a real part of the city and a different checklist.
Can you review the policy without an office in Hollywood?
Yes. WhatsApp or email the declarations page. We serve Hollywood from Florida City, about 70 minutes away in light traffic, and we say so on purpose. There is no local office to visit except by appointment in Florida City.
More for this area
Ready for a second opinion on your coverage?
Leave your number and a licensed agent will call you back, within an hour during business hours.
Have an agent call meCall (305) 859-3953
📄 Send us your policy – we'll check your coverage
A photo of the first page (declarations page) is enough.
This article is general information, not legal advice or policy language. Coverage depends on the terms, limits and exclusions of your policy, and eligibility rules can change. Talk with a licensed agent about your situation.
Sources
Facts on this page were checked against these sources on October 21, 2026.
- National Hurricane Center: Tropical Cyclone Report, Hurricane Wilma (2005)
- Florida Building Code, Building (8th ed., 2023), Chapter 16, Section 1620: High-Velocity Hurricane Zones (Miami-Dade and Broward)
- Broward County Board of Rules and Appeals (local building code administration)
- Broward County: FEMA flood zone maps (effective July 31, 2024)
- U.S. Census Bureau, ACS 2020–2024 5-year: population, housing, vacancy, commuting, nativity and language (B01003, B25024, B25034, B25035, B25003, B25004, B08303, B08013, B05002, C16001), Hollywood
- City of Hollywood: Joseph Young’s plan, the lakes along Hollywood Boulevard, and the 1925 Intracoastal bridge
- City of Hollywood CRA: FEMA flood maps effective July 31, 2024; more than 11,000 properties added to the Special Flood Hazard Area, 2,115 removed from the mandate
- Florida Department of Financial Services: wind mitigation inspection form OIR-B1-1802
- Florida Statutes s. 627.0629: required wind mitigation credits
- Florida Statutes s. 627.7011: roof-age rule (15 years), law and ordinance coverage, replacement cost
- Florida Statutes s. 627.701: hurricane deductible options and the calendar-year rule
- Florida Statutes s. 627.70132: property claim notice deadlines (1 year, 18 months)
- Florida Statutes s. 718.111(11): what a condo association’s master policy must and need not cover
- Florida Statutes s. 627.714: condo unit owner loss assessment coverage
- Florida DBPR: condo milestone inspections and structural integrity reserve studies
- FloodSmart.gov (NFIP): what flood insurance covers
- My Safe Florida Home: state hurricane-hardening inspections and grants
Areas we serve
We serve these Miami-Dade and Broward communities from our Florida City office, in person by appointment and by phone, WhatsApp, text and email.