
If someone gets hurt at your home, is your family protected?
Most people buy home insurance for hurricanes and fires. The same policy also protects you if a guest is hurt at your house. Here is how that works in plain words, and where the gaps are.
The short version
- Home insurance has a part called personal liability. It can pay if someone is hurt at your home and you are found responsible, up to a limit.
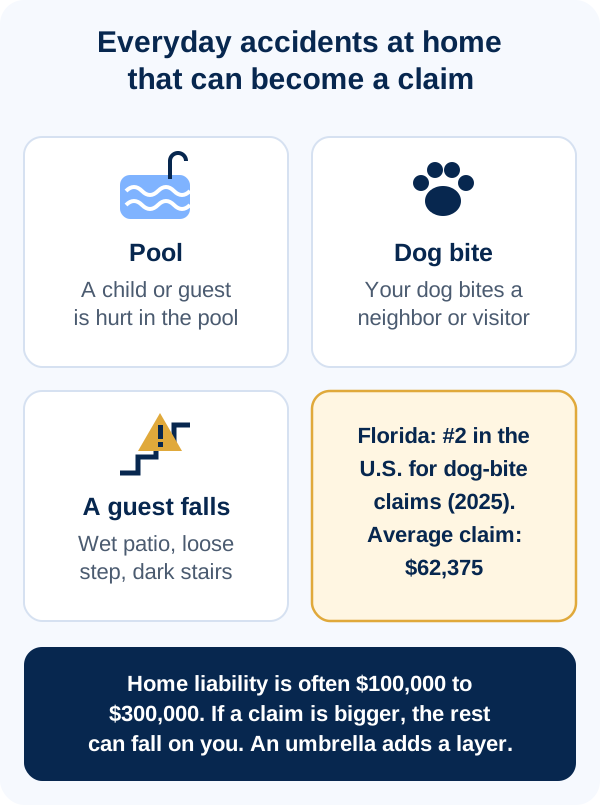
- That limit is often $100,000 to $300,000. If a claim is bigger, the rest can fall on you.
- Florida had the 2nd most dog-bite claims in the U.S. in 2025: 2,347 claims, about $62,375 each on average.
- In Florida, drowning is the leading cause of accidental death for children ages 1 to 4, and home pools are where most children are likely to drown.
- An umbrella policy adds an extra layer of liability on top of your home and car policies.
How liability on your home policy works
Think of your home policy as having two jobs. One job is your house and your things. The other job is you. If someone is hurt at your place and you are responsible, the liability part can help pay.
It can help pay the other person's medical bills and lost pay. In most policies it also pays for your legal defense if they file a claim against you. It pays only up to the limit on your policy.
Many policies also have a small medical payments to others part. It pays small medical bills for a hurt guest, no matter who was at fault.
Three everyday stories
None of these people did anything unusual. That is the point: most claims start on a normal day.
Where the gap is
The Insurance Information Institute says home liability limits are typically $100,000 to $300,000. If a claim goes over the limit, the owner is responsible for the rest.
Serious injuries can cost much more than that. A real Florida case shows how far apart the numbers can be: a $100,000 policy and an $8.47 million verdict. Read it on our Umbrella & wealth protection page.
What is at stake
Your savings, your investments, a rental property or your business, and your peace of mind. An umbrella policy adds an extra layer, for example $1 million, above your home and car limits.
And the house itself?
The part of your policy for the house (dwelling coverage) should be enough to rebuild it at today's prices, not what you paid for it. Building costs change, so check it every year.
A regular home policy does not cover flood. Flood needs its own policy. Ask us if you are not sure what you have.
The numbers behind it
Check your own policy in 2 minutes
- On the first page of your home policy, find Personal Liability (often called Coverage E). Write down the limit.
- Find Medical Payments to Others (often Coverage F).
- Do you have a pool, a trampoline, a dog, a boat or a home you rent out? Tell your agent. Some of these can change what is covered.
- Do you have savings, a teen driver or a business? Ask about an umbrella policy.
- Check that the dwelling limit is enough to rebuild your home at today's prices.
- Not sure? Send us your policy and we'll check your coverage.
Keep reading
Frequently asked questions
What does home liability coverage pay for?
If someone is hurt at your home, or you accidentally damage someone else's property, and you are responsible, it can help pay their medical bills, lost pay and other damages, plus your legal defense in most policies. It pays up to your limit.
Does my home insurance cover my dog?
Home and renters policies typically cover dog-bite liability up to the limit. Some insurers will not cover certain breeds, and some decide case by case. Tell us about your dogs so we can check your policy.
Is my pool a problem for my insurance?
Injuries to guests at your pool are usually part of your home liability coverage, up to the limit. Some insurers ask for safety features such as a fence. Tell us about your pool so there are no surprises.
What happens if a claim is bigger than my limit?
Your insurance pays up to the limit. The rest can become your personal responsibility. That is exactly what an umbrella policy is for.
Do renters and condo owners have liability coverage?
Yes, renters and condo policies usually include personal liability too. The same rule applies: it pays up to the limit you chose.
Does the liability part cover injuries to my own family?
No. Liability is for other people. Your own family is protected by health insurance, and for a lost paycheck, by planning such as life insurance.
Is your home liability limit high enough?
Send us your policy and we'll check your coverage. We'll show you your liability limit, what it means for your family, and whether an umbrella makes sense. We call back within 1 hour during business hours.
Send us your policy and we'll check your coverage →📄 Send us your policy – we'll check your coverage
A photo of the first page (declarations page) is enough.
M&K Agency · 33550 S Dixie Hwy, Suite 102, Florida City, FL 33034 · Mon–Fri 9–6, Saturday by appointment · Florida license #L109526
Talk to a licensed agent
Takes 30 seconds. A real agent calls you back fast.
This page is general information, not legal advice and not policy language. What is covered depends on your policy, its limits and its exclusions. Stories marked "Example" are made up to explain the idea, and the real case we mention comes from a public court record. Every situation is different, and no one can promise how a claim will turn out.
Sources
Facts on this page were checked against these sources on October 3, 2026.