✦ In God We Trust · We build our future together ✦
Car insurance · Uninsured motorist (UM)

If a driver with no insurance hits you, who pays your bills?

In Florida, drivers don't have to carry insurance for the injuries they cause. Here is what that can mean for your paycheck, your health and your family, and the coverage on your own policy that can step in.

English · Español · По-русски
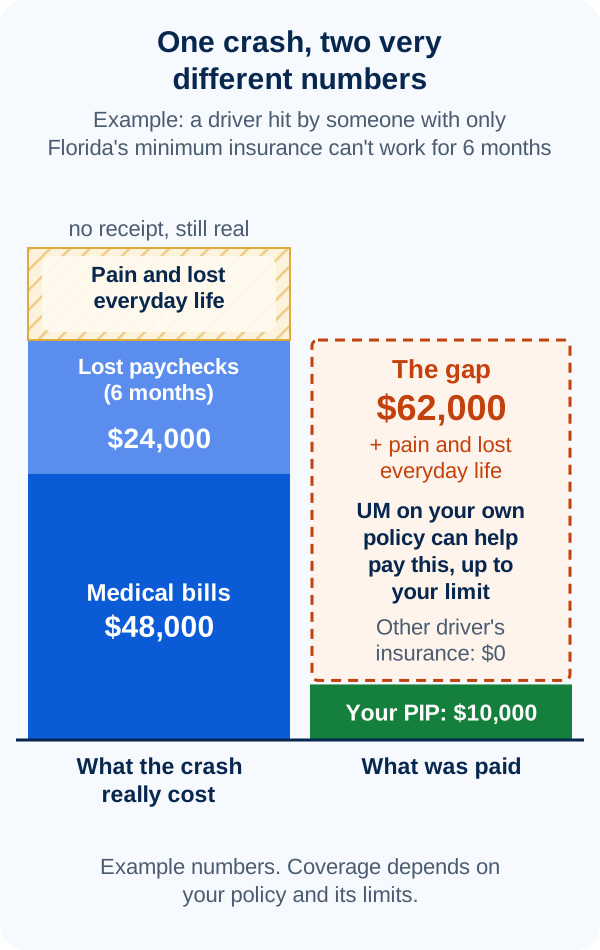
Bar chart, example numbers. What a crash really cost: $48,000 in medical bills, $24,000 in lost paychecks over 6 months, plus pain and lost everyday life, which has no receipt. What was paid: $10,000 from the injured driver's own PIP and $0 from the other driver's insurance. The gap of $62,000 plus pain is what uninsured motorist coverage on your own policy can help pay, up to your limit.

The short version

  • Florida's minimum car insurance is $10,000 of PIP and $10,000 of property damage. It does not require insurance for injuries you cause to other people.
  • About 1 in 5 Florida drivers had no insurance at all in 2023 (20.6%), one of the highest rates in the country.
  • Your own PIP pays up to $10,000 in total: 80% of medical bills and 60% of lost pay, all from the same pot.
  • Uninsured motorist coverage (UM) is on your own policy. If the other driver has no insurance or too little, it can pay your medical bills, your lost pay and, for serious injuries, pain and suffering, up to your limit.

A story: hit at a red light, out of work for six months

Numbers are easier to understand as a story. Here is a common kind of Florida crash.

When the paycheck stops

For most families, the biggest loss after a bad crash is not the car. It's the paycheck. Rent and groceries don't wait until you heal.

PIP helps, but only a little. By Florida law it pays 60% of the income you lose and 80% of your medical bills, and both come out of the same $10,000. If a doctor doesn't find an emergency medical condition, the limit can drop to $2,500. You also have to get care within 14 days of the crash.

What about Social Security disability? It pays only if your condition is expected to last at least a year or to end in death. There is generally a 5-month waiting period, and a decision usually takes 6 to 8 months. A broken leg that heals in eight months would not qualify.

Good to know

Social Security says a 20-year-old worker has a 1 in 4 chance of becoming disabled before full retirement age.

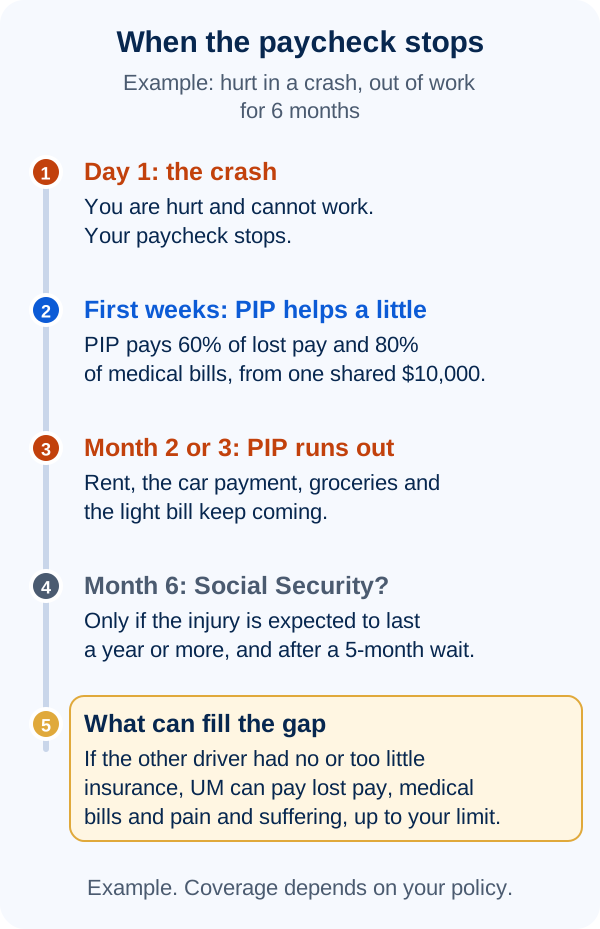
Timeline, example. Day 1: the crash; you are hurt and your paycheck stops. First weeks: PIP pays 60% of lost pay and 80% of medical bills from one shared $10,000. Month 2 or 3: PIP runs out while rent, the car payment, groceries and the light bill keep coming. Month 6: Social Security disability only if the injury is expected to last a year or more, and after a 5-month wait. What can fill the gap: if the other driver had no or too little insurance, UM can pay lost pay, medical bills and pain and suffering, up to your limit.
Example timeline. PIP numbers come from Florida law; the Social Security rules come from the SSA.

Two kinds of losses: with a receipt and without one

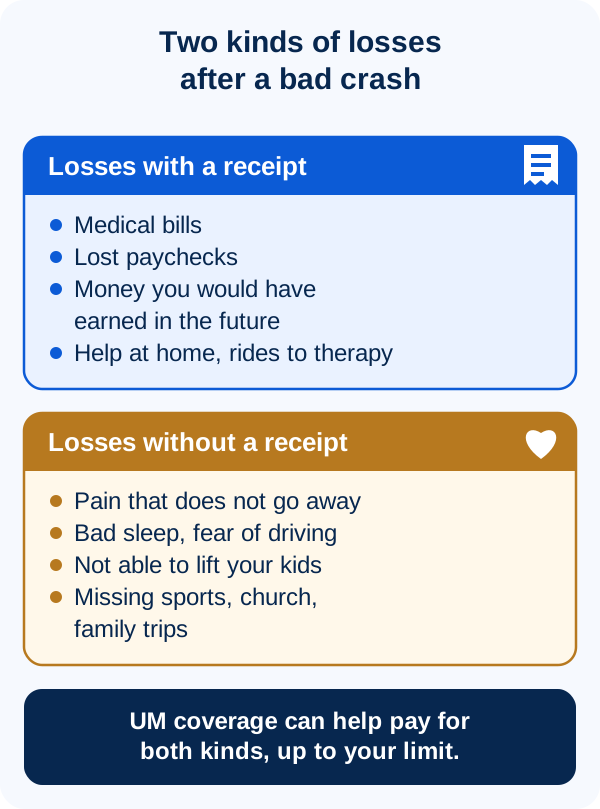
Some losses come with a bill: the hospital, the therapy, the paychecks you missed, and the money you would have earned later if you can't go back to the same work.

Other losses don't come with a receipt, but they are just as real: pain, sleepless nights, not being able to hold your kids, or missing the job, the church and the sports you love.

UM can help with both. Under Florida law, pain and suffering is paid only for serious injuries, such as a permanent injury, serious scarring or a death.

These losses are huge across the country too. In 2019, U.S. crashes cost about $340 billion in money losses such as medical care and lost work, according to NHTSA. When the government also counted pain and lost quality of life, the total was nearly $1.4 trillion.

Two cards. Losses with a receipt: medical bills, lost paychecks, money you would have earned in the future, help at home and rides to therapy. Losses without a receipt: pain that does not go away, bad sleep and fear of driving, not being able to lift your kids, missing sports, church and family trips. UM coverage can help pay for both kinds, up to your limit.
The law calls these "economic" and "non-economic" damages. In plain words: losses with and without a receipt.

What if the driver drives away?

Florida had 97,519 hit-and-run crashes in 2024, according to the state highway safety department. Most damaged only property. The rest involved people who were hurt or killed.

In many policies, a hit-and-run driver who is never found is treated like an uninsured driver, so UM can apply. Report the crash to the police right away, and check your policy for the exact rules.

Real Florida cases: what serious injuries can cost

These come from public court records. We share them to show how big real losses can be, not to suggest that anyone should sue. Every case is different.

Real case

Permanent injuries from an underinsured driver

Broward County · Florida Fourth District Court of Appeal, 2020

What happened
A driver was hit by an underinsured driver and was left with permanent injuries. The other driver's insurance was not enough, so he made a claim on the UM coverage of his own policies. The only question for the jury was how much the crash had cost him.
What was decided
The jury set his losses at $810,000 in lost earnings, $369,629 in medical expenses and $400,000 for pain and suffering: $1,579,629 in total. The appeals court kept the jury's numbers. The final amount was lower because money he had already received from other insurance was subtracted.
What it shows
Lost earnings were the biggest part, more than half of the total. A serious injury is first of all a paycheck problem.

Source: Florida Fourth District Court of Appeal, opinion in cases 4D18-3652 and 4D19-118 (June 24, 2020) (PDF)

Real case

A $10,000 policy and a life-changing crash

Hillsborough County · Florida Supreme Court, 2004 (crash in 1990)

What happened
A driver who had been drinking crossed the center line and hit a car carrying a mother and her young daughter. The mother died. The daughter was badly hurt, with more than $30,000 in medical bills, and her father missed a lot of work. The car that caused the crash was insured for only $10,000 per person and $20,000 per crash.
What was decided
Juries later set the damages at $911,400 for the mother's death and $500,000 for the daughter's injuries, about $1.4 million in total. That is about 70 times the $20,000 of coverage.
What it shows
Low limits pay only a small part of a serious crash. For the family that is hit, UM on their own policy is what can help fill the gap. For the driver at fault, the rest can become a personal debt (see Umbrella & wealth protection).

Source: Florida Supreme Court, opinion in case SC01-2846 (2004), full text

The numbers behind it

20.6%of Florida drivers were uninsured in 2023, about 1 in 5. The U.S. rate was 15.4%.Source: Insurance Information Institute
$0of bodily injury coverage is required for most Florida drivers. The minimum is $10,000 PIP and $10,000 property damage.Source: Florida Department of Highway Safety and Motor Vehicles
$10,000is the most PIP pays in total. Medical bills (80%) and lost income (60%) share that one limit.Source: Florida Statutes, section 627.736 (PIP benefits)
97,519hit-and-run crashes happened in Florida in 2024.Source: FLHSMV news release (Feb. 3, 2025)
1 in 4is the chance a 20-year-old worker becomes disabled before full retirement age, says Social Security.Source: Social Security Administration
$340 billionwas the money cost of U.S. crashes in 2019. Counting pain and lost quality of life: nearly $1.4 trillion.Source: NHTSA

Check your own policy in 2 minutes

  • Find the first page of your policy (the declarations page). Look for the words Uninsured Motorist or UM.
  • If UM isn't listed, or it says rejected, you don't have it. In Florida it can only be turned down in writing.
  • Look at the numbers. For example, 50/100 means up to $50,000 per person and $100,000 per crash.
  • Look for stacked or non-stacked. With more than one car, stacked UM adds up the limit for each car.
  • Compare UM with your bodily injury limits. In Florida, UM matches them unless someone chose lower limits.
  • No bodily injury coverage on your policy? Then you most likely have no UM either. Ask us.
  • Not sure? Send us a photo of that first page. We'll go over it with you in English, Spanish or Russian.

Keep reading

Frequently asked questions

What is uninsured motorist coverage, in plain words?

It is coverage on your own car policy that protects you, not the other driver. If someone hits you and has no insurance, or not enough, UM can pay your medical bills, your lost pay and, for serious injuries, pain and suffering. It pays up to the limit you chose.

Is UM required in Florida?

No. But if your policy has bodily injury liability, Florida law says UM comes with it unless it is turned down in writing. It's worth checking whether a rejection form was signed when your policy started.

Doesn't my health insurance cover this?

Health insurance can help with medical bills. It doesn't replace your paycheck or pay for pain and suffering, and you may still owe deductibles and copays. UM is meant for the losses the other driver should have paid.

Does UM pay to fix my car?

No. UM is for injuries to people. Damage to your car is usually paid by collision coverage on your own policy.

What is the difference between stacked and non-stacked UM?

If you have more than one car, stacked UM lets you add the UM limit of each car together. Non-stacked gives you the limit of one car. In Florida, UM is stacked unless you choose non-stacked in writing.

Does UM pay right away, like PIP?

Usually not. PIP pays bills as they come in. UM is usually paid as one lump sum once the full extent of your treatment is known. That is one more reason to plan for the months in between.

What if it was a hit-and-run?

Many policies treat a hit-and-run driver who is never found as an uninsured driver, so UM can apply. Report the crash to the police right away and check your policy for the exact rules.

Do you have UM? Let's check together.

Send us your policy and we'll check your coverage. A licensed agent will explain what you have in plain words. We call back within 1 hour during business hours.

Send us your policy and we'll check your coverage →

📄 Send us your policy – we'll check your coverage

A photo of the first page (declarations page) is enough.

M&K Agency · 33550 S Dixie Hwy, Suite 102, Florida City, FL 33034 · Mon–Fri 9–6, Saturday by appointment · Florida license #L109526

Talk to a licensed agent

Takes 30 seconds. A real agent calls you back fast.

🔒 Your info stays private. No spam, ever.