
Home and condo insurance in Fort Lauderdale, for canals, towers and a flood that was not a hurricane.
Las Olas, the New River, houses west of I-95 and condos on the beach. Send us the policy. We read it against the building and the flood panel. English, Spanish or Russian.
Talk to a licensed agent
Takes 30 seconds. A real agent calls you back fast.
A county seat built on canals
Fort Lauderdale is the Broward county seat. The 2020–2024 Census estimates count about 101,700 housing units. About 34% are detached houses. About 28% are in buildings with 50 or more units. Buildings with two or more units hold about 60% of the stock, from beach towers and downtown condominiums to smaller buildings inland. Of the occupied homes, about 54% are owner-occupied. About 12,700 units, roughly one in eight, were vacant for seasonal or occasional use. The median year built is 1973. About 65% of units were built before 1980, and about 44% before 1970. Census table C16001 counts about 1,900 residents age 5 and older who speak Russian, Polish or another Slavic language at home, about 1.1% of that age group. The line is not a count of Russian alone.
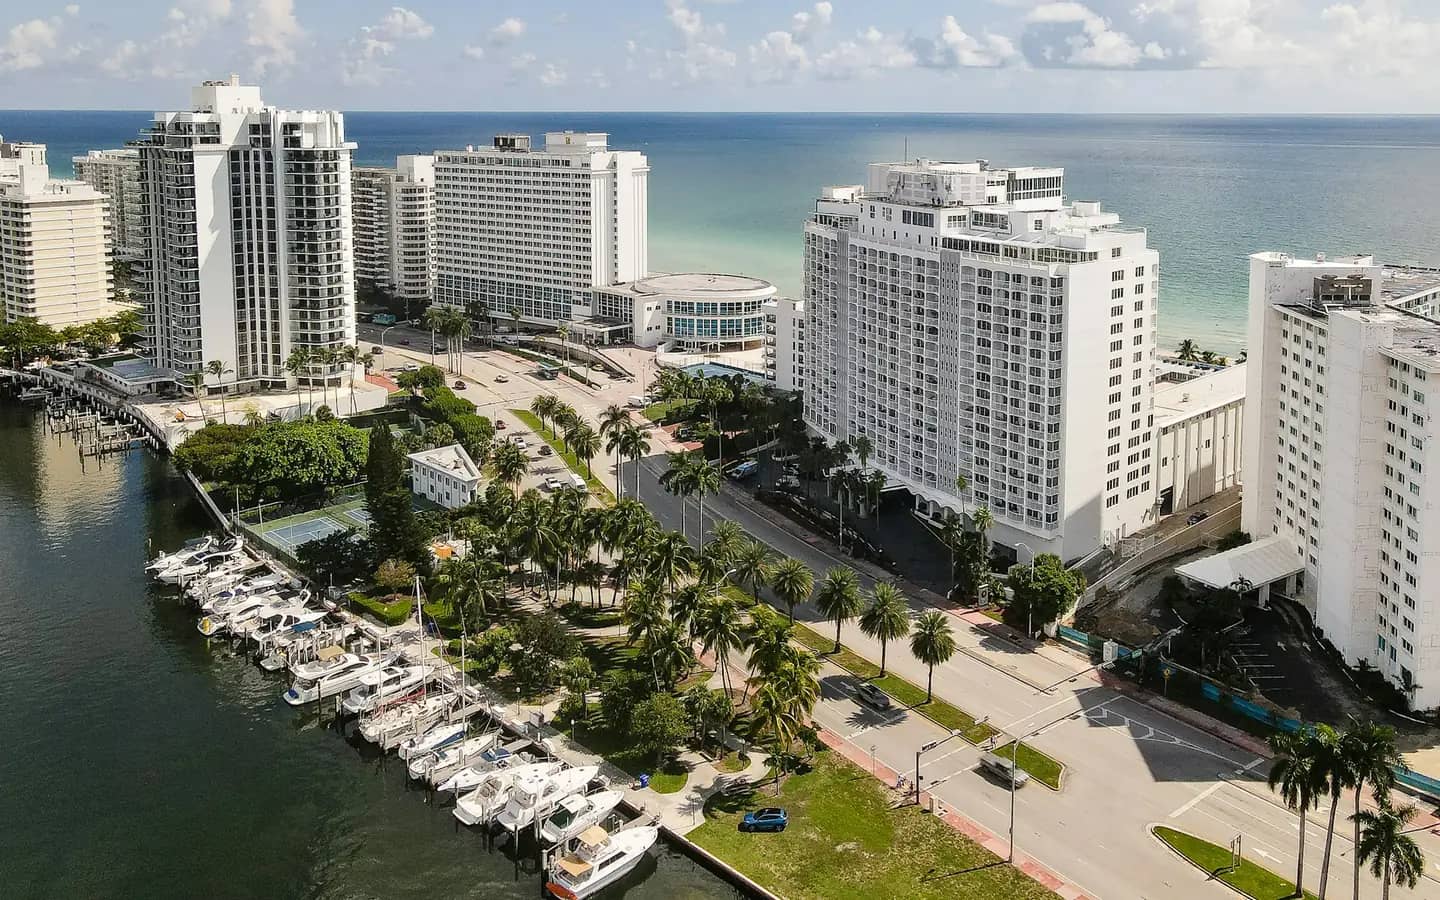
The geography is water as much as streets. The New River crosses downtown. Las Olas Boulevard runs from the beach toward the river. Las Olas Isles, Rio Vista and the finger canals north and south of the river put living rooms a few feet above a seawall. A1A is the beach. I-95 and Federal Highway (US-1) are the inland edges of that coastal strip, and the housing west of I-95 is a different building: more houses, fewer towers, still on a drainage system that filled up in a single afternoon in 2023.
Broward is in the High-Velocity Hurricane Zone. Florida Building Code section 1620 sets the design wind speed by risk category: 156 mph for Category I, 170 mph for Category II, 180 mph for Category III and 185 mph for Category IV. A typical house is Category II. Windows, doors, shutters and roofing in this zone need an HVHZ product approval. Local code interpretations go through the Broward County Board of Rules and Appeals. Most of the city’s homes are older than the code those products were tested under.
What we check on a Fort Lauderdale home or condo policy
- The form. A house on a canal is usually an HO-3. A unit in a tower is an HO-6. The wrong form is the first gap.
- Wind mitigation (OIR-B1-1802) on a house: roof shape, deck, roof-to-wall connection and opening protection that meets the HVHZ rules. Insurers must give the credits the statute requires for what the form documents.
- The hurricane deductible, $500 or 2%, 5% or 10% of the dwelling limit, once per calendar year. On a condo, the surprise is often the association’s deductible, split among owners.
- Roof age and settlement. Since July 1, 2022, an insurer cannot refuse a policy only because the roof is under 15 years old. A 1960s or 1970s roof can still be actual cash value if the form says so.
- On a condo, the master policy’s exclusions, then the HO-6 for interiors and belongings, plus loss assessment above the $2,000 floor.
- Milestone and SIRS assessments, which insurance generally does not pay. Many buildings here are decades past 30 years.
- Seasonal and vacant-unit conditions, including how long the home can sit empty. About one in eight units was vacant for seasonal use.
- Flood on a separate policy. The April 12, 2023 rainfall was not covered by a homeowners form. Broward’s FIRMs took effect July 31, 2024.
The flood that closed City Hall was rain
On April 12 and 13, 2023, NOAA recorded 15 to 25 inches of rain between noon and midnight across Fort Lauderdale, Hollywood, Dania Beach and Wilton Manors. The highest measured total was 25.91 inches at a gauge at Fort Lauderdale-Hollywood International Airport. More than 1,100 buildings in Fort Lauderdale were damaged, 766 of them with major damage. The storm database says City Hall took major water damage and was considered a complete loss. Surveyed water marks inside homes in the Edgewood and Melrose Park neighborhoods were over 3 feet. About 600 residents were displaced. This was rainfall on a city of canals and storm drains, not a hurricane storm surge.
A homeowners policy and an HO-6 exclude flood. The water in those houses was not a wind claim because a window failed. It was flood, and flood is a separate policy, usually through the NFIP or a private flood form. An NFIP policy usually takes 30 days to start unless it is tied to a loan closing. The program caps are $250,000 for the building and $100,000 for contents. Those caps are not a rebuilding estimate. Broward’s current FEMA flood maps took effect on July 31, 2024. A lot can be in a different zone than the map the owner remembers from before that date. Canal streets and inland neighborhoods both need the panel for the address. We read the policy you have. We do not quote a price on this page.
Wind on the towers, and the glass Wilma broke
Hurricane Wilma, in October 2005, is the wind event this downtown still shows in old photographs of missing windows. The National Hurricane Center found that parts of Broward likely had Category 2 conditions, with gusts near 100 knots at the standard 10-meter height and stronger wind on upper floors. During Hurricane Irma in 2017, the National Weather Service reported gusts of about 80 to 100 mph across most of coastal and metro Broward, with less structural damage than Wilma and widespread tree and fence damage. Opening protection that was added after Wilma should show up in the association’s records and, for a house, on the wind-mitigation form. Insurers must give credit for the features the form documents. A missing form is a gap, not a reason for us to guess the credit.
Hurricane deductibles are offered at $500 or at 2%, 5% or 10% of the dwelling limit and apply once per calendar year. For a policy issued or renewed since July 1, 2022, an insurer cannot refuse it only because the roof is under 15 years old. Law and ordinance coverage is the part that can pay to rebuild to the current HVHZ code rather than to replace a 1970s roof as it was. On a house from before 1970, that gap can be large. Check the limit.
Condo units, milestone inspections and the assessment
Florida Statute 718.111(11) requires the association to insure the building and to exclude the interior of the unit: floor, wall and ceiling coverings, fixtures, appliances, the water heater, cabinets, countertops, window treatments and personal property. That interior is an HO-6, with your liability and loss of use. Statute 627.714 requires at least $2,000 of loss-assessment coverage for a share of a covered loss to property the association insures. A high-rise hurricane deductible divided among the owners can exceed that floor. Buy the limit with the form in front of you, not from a slogan.
Buildings of three or more habitable stories need a milestone inspection, generally at 30 years and every 10 years after, or at 25 if the local official requires it, plus a structural integrity reserve study at least every 10 years. The certificate of occupancy is the clock. With a median year of 1973 and nearly two-thirds of units built before 1980, a large share of Fort Lauderdale condominiums are already inside that schedule. An assessment to fund reserves or to pay for concrete and balcony repairs the inspection required is generally not a loss-assessment claim. Send the notice, the master-policy certificate and your HO-6. We will say which of those three the form might respond to. Property claims have their own clock: notice of a new claim is generally due within one year, supplemental claims within 18 months, and a loss-assessment claim on the timetable in the statute and the form. M&K Agency is family-owned, with a team of 12 and more than 5,000 clients across Florida. Send us your policy and we’ll check your coverage.
Serving Fort Lauderdale from Florida City
We do not have an office in Fort Lauderdale. The office is at 33550 S Dixie Hwy, Suite 102, Florida City, FL 33034, about 63 miles south. In light traffic the drive is roughly 80 minutes by the Turnpike and I-95, and longer at rush hour. Clients send the declarations page, photos and, for a condo, the association certificate by WhatsApp, text or email. A visit is by appointment.
Hours are Monday to Friday, 9 to 6, and Saturday by appointment. Call (305) 859-3953 or WhatsApp (971) 998-7313. During business hours an agent calls back within an hour.
33550 S Dixie Hwy, Suite 102
Florida City, FL 33034
English · Español · По-русски
Home insurance in Fort Lauderdale: common questions
Did homeowners insurance pay the April 2023 flood?
The homeowners form and the HO-6 exclude flood. NOAA recorded extreme rainfall, major damage to more than 700 Fort Lauderdale buildings, and City Hall treated as a complete loss. That water is a flood claim, on a separate policy, if one was in force. Wind-driven rain through a failed opening can be a different claim. The form decides. Send it before anyone tells you the loss is covered.
Which flood map is in effect?
Broward’s FEMA flood maps took effect July 31, 2024. Use the panel for the address. A canal lot and a house west of I-95 can both have changed zone since the prior map. Flood is not part of the homeowners policy.
The association assessed me after a milestone inspection. Is that covered?
Generally no. Loss-assessment coverage responds to certain assessments for a covered property loss or, depending on the form, the association’s deductible. It is at least $2,000, and more only if you bought more. An assessment to fill reserves or to pay for required structural repairs is a different bill. Send the notice and both policies, yours and the association’s.
What wind speed is my house designed for?
Section 1620 of the Florida Building Code lists Broward’s HVHZ speeds by risk category: 156, 170, 180 and 185 mph. A typical house is Risk Category II, at 170 mph. Older houses were not all built to that figure. The wind-mitigation form documents what is actually on the building. We do not invent a speed for a house we have not inspected.
We use the condo a few months a year. Can you still review the policy?
Yes. Seasonal and vacant-unit rules are in the policy, including how long the unit may sit empty. Send the declarations page and the association certificate by WhatsApp or email. We serve Fort Lauderdale from Florida City, about 63 miles and roughly 80 minutes away in light traffic. We do not have an office in the city.
More for this area
Ready for a second opinion on your coverage?
Leave your number and a licensed agent will call you back, within an hour during business hours.
Have an agent call meCall (305) 859-3953
📄 Send us your policy – we'll check your coverage
A photo of the first page (declarations page) is enough.
This article is general information, not legal advice or policy language. Coverage depends on the terms, limits and exclusions of your policy, and eligibility rules can change. Talk with a licensed agent about your situation.
Sources
Facts on this page were checked against these sources on November 4, 2026.
- U.S. Census Bureau, ACS 2020–2024 5-year: population, housing, vacancy, commuting, age, nativity and language (B01003, B01001, B25024, B25034, B25035, B25003, B25004, B08303, B08013, B05002, C16001), Fort Lauderdale
- Florida Building Code, Building (8th ed., 2023), Chapter 16, Section 1620: High-Velocity Hurricane Zones (Miami-Dade and Broward)
- Broward County Board of Rules and Appeals (local building code administration)
- Broward County: FEMA flood zone maps (effective July 31, 2024)
- Florida Department of Financial Services: wind mitigation inspection form OIR-B1-1802
- Florida Statutes s. 627.0629: required wind mitigation credits
- Florida Statutes s. 627.7011: roof-age rule (15 years), law and ordinance coverage, replacement cost
- Florida Statutes s. 627.701: hurricane deductible options and the calendar-year rule
- Florida Statutes s. 627.70132: property claim notice deadlines (1 year, 18 months)
- Florida Statutes s. 718.111(11): what a condo association’s master policy must and need not cover
- Florida Statutes s. 627.714: condo unit owner loss assessment coverage
- Florida DBPR: condo milestone inspections and structural integrity reserve studies
- FloodSmart.gov (NFIP): what flood insurance covers
- National Hurricane Center: Tropical Cyclone Report, Hurricane Wilma (2005)
- National Weather Service Miami: Hurricane Irma local report (winds and coastal inundation in Miami-Dade, Broward and Palm Beach)
- NOAA NCEI Storm Events: April 12–13, 2023 flash flood in Broward, 25.91 inches at the Fort Lauderdale airport gauge, building and vehicle damage in Fort Lauderdale
Areas we serve
We serve these Miami-Dade, Broward and Palm Beach communities from our Florida City office, in person by appointment and by phone, WhatsApp, text and email.