
Life insurance in Florida: so your family keeps the home and the plan if your paycheck stops.
Quick answer: Life insurance replaces the income your family would lose if you died. Nearly half of Americans say their household would struggle to pay the bills within six months of losing the main earner. A personal agent helps you work out how much coverage fits your family, name the right beneficiaries, and helps them with the claim.
Talk to a licensed agent
Takes 30 seconds. A real agent calls you back fast.
Most families think about life insurance at a funeral. The better time is now, while you can still choose. The real question is not “Do I need a policy?” but “If my paycheck stopped tomorrow, how long would my family be OK?”
This page walks through that question in plain words: how much income to replace, why coverage through work may not be enough, how beneficiaries work under Florida law, and what we do when your family needs us.
Life insurance in the U.S.: what the numbers say
- 47%of American adults say they would have trouble paying living expenses within 6 months of their primary wage earner’s death.Source
- 29%say they would stay financially secure for more than 2 years if a primary wage earner died.Source
- 38%of adults, about 92 million people, say they need life insurance or need more of it.Source
- 47%of people who have life insurance get it through work. That coverage is tied to the job.Source
Where Florida families get caught short
Only the coverage from work
Group life through an employer is often a set amount, and it may end or change when you leave the job. Check whether it can be continued or converted.
The stay-at-home parent has none
If the parent at home died, the family would have to pay for childcare, driving and the work of running a house.
Outdated beneficiaries
A marriage, a divorce or a new baby can leave the wrong person named, or nobody. If the policy pays your estate, the money can go through probate.
Life insurance options to ask about
Term life
Coverage for a set number of years, for example while the children are growing up or until the mortgage is paid.
Permanent life (whole or universal)
Coverage meant to last for life while it is kept in force. Many permanent policies build cash value.
Riders
Add-ons such as coverage for a child, a waiver of payments after a disability, or access to part of the benefit if terminally ill, where offered.
Final expense coverage
A smaller policy meant for funeral and end-of-life costs, so the family does not have to pay them.
Coverage outside of work
An individual policy you own, that stays with you when you change jobs.
Beneficiary planning
Primary and backup beneficiaries, and how to handle minor children, reviewed with your agent.
These are general descriptions. Availability, terms and exclusions depend on the policy and on underwriting.
Start with income replacement
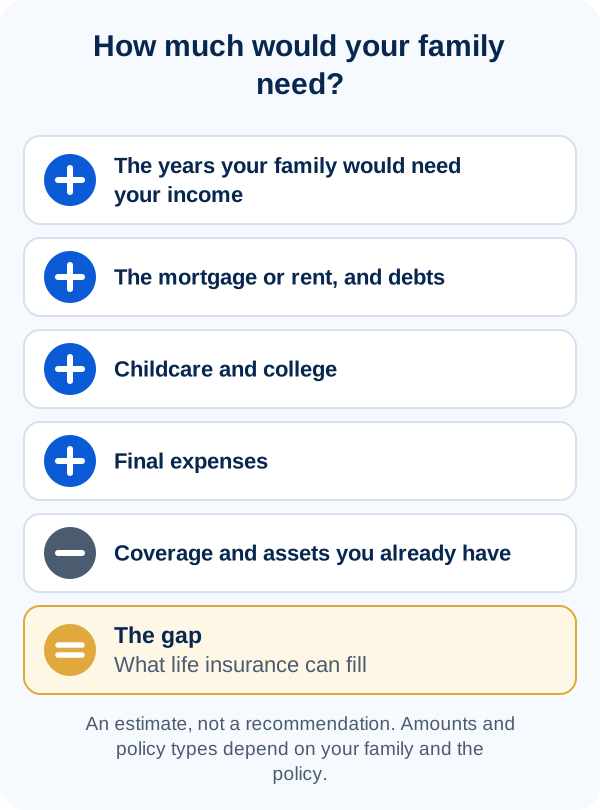
Among the top reasons Americans give for owning life insurance are burial and final expenses, leaving an inheritance and replacing the income of a wage earner (LIMRA and Life Happens, 2026). For a working family, income replacement is usually the biggest number. A simple way to think about it:
- How many years would your family need your income? Until the youngest finishes school, or until your spouse retires?
- What would they need to pay off or keep paying: the mortgage or rent, other debts, credit cards?
- What else is coming: childcare, college, caring for a parent?
- Add final expenses.
- Subtract what you already have: coverage through work, other policies, assets.
The calculator below gives you a starting point. An agent can then help you decide how much coverage and which type fit your family. Nearly a quarter of Americans say they haven’t bought life insurance because they don’t know how much they need or what type to buy; that is exactly what the conversation is for.
What Florida law says about beneficiaries and your policy
- When a Florida resident dies, life insurance paid to a named beneficiary goes to that person and is generally protected from the claims of the insured’s creditors. If it is payable to the insured’s estate, it becomes part of the estate (s. 222.13).
- The cash surrender value of a policy on a Florida resident is also generally protected from creditors (s. 222.14).
- A life policy becomes incontestable after it has been in force for 2 years during the insured’s lifetime, except for nonpayment and certain disability and accident benefits (s. 627.455). Answer the application honestly and completely.
- For an insured 64 or older whose policy has been in force at least a year, you can name a secondary person to be notified, and the insurer must mail notice to the owner and that person at least 21 days before the policy lapses for nonpayment (s. 627.4555). It is a simple way to keep a parent’s policy from lapsing by accident.
Already have a policy?
Pull it out and read the beneficiary page. If it names an ex-spouse, a minor child directly or nobody at all, talk to your agent this week. Send us your policy and we’ll check your coverage.
Human Life Value calculator
A simple estimate of how much life insurance coverage might make sense for your situation — not a quote, just a starting point for the conversation.
This is a simplified estimate for educational purposes only, not a formal needs analysis and not a quote. Talk to a licensed agent to find the right coverage for your situation.
A ten-minute life insurance check
- Do you know how much coverage you have, including through work?
- Would it cover several years of your income, plus the mortgage or rent?
- Does your spouse or partner, including a stay-at-home parent, have coverage?
- Are your primary and backup beneficiaries current?
- Would your coverage end if you left your job?
- If a parent is 64 or older, have they named a secondary person for lapse notices?
A personal agent when your family needs it most
M&K Agency is a family-owned agency in Florida City with more than 5,000 clients across Florida and a team of 12 who speak English, Spanish and Russian. We sit down with you, in person or by phone, to work out what your family would need.
And if the worst happens, your family calls us. We help them find the policy, gather the documents and file the claim, and we explain each step in their language.
33550 S Dixie Hwy, Suite 102
Florida City, FL 33034
English · Español · По-русски
Life insurance in Florida: common questions
How much life insurance do I need?
Start with the years of income your family would need, add the mortgage or rent, debts, childcare, college and final expenses, then subtract the coverage and assets you already have. The calculator on this page gives a starting estimate; an agent can help you refine it.
Is life insurance through work enough?
Often not. Group coverage is usually a set amount, and it may end or change when you leave the job. Many families add an individual policy they own.
Is life insurance protected from creditors in Florida?
Generally, yes. Under s. 222.13, Florida Statutes, proceeds paid to a named beneficiary are exempt from the claims of the insured’s creditors unless the policy or an assignment says otherwise; if the policy pays the estate, the money becomes part of the estate. Cash surrender value is also generally exempt under s. 222.14. For your situation, ask an attorney.
What is the difference between term and permanent life insurance?
Term life covers a set number of years. Permanent life, such as whole or universal life, is meant to last for life while it is kept in force, and many permanent policies build cash value. Which one fits depends on your goals.
Can an insurer deny a claim because of something on my application?
Under Florida law, a life policy becomes incontestable after it has been in force for 2 years during the insured’s lifetime, with some exceptions such as nonpayment. Before then, misstatements on the application can matter, so answer every question honestly.
Will you help my family with a claim?
Yes. Your family can call us or message us on WhatsApp. A licensed agent helps them file the claim and explains each step in English, Spanish or Russian.
Keep reading
Send us your policy and we’ll check your coverage
A licensed agent reads your current policy, shows you the gaps in plain words and helps you fix them. Call us, or leave your number and we’ll contact you within an hour during business hours.
Have an agent call meCall (305) 859-3953
📄 Send us your policy – we'll check your coverage
A photo of the first page (declarations page) is enough.
This article is general information, not legal advice or policy language. Coverage depends on the terms, limits and exclusions of your policy, and eligibility rules can change. Talk with a licensed agent about your situation.
Sources
Facts on this page were checked against these sources on October 3, 2026.
- LIMRA and Life Happens: 2026 Insurance Barometer, Facts About Life Insurance (PDF)
- Florida Statutes s. 222.13 (2026): life insurance proceeds and creditors
- Florida Statutes s. 222.14 (2026): cash surrender value of life insurance exempt from creditors
- Florida Statutes s. 627.455 (2026): incontestability of life insurance after 2 years
- Florida Statutes s. 627.4555 (2026): secondary notice before a life policy lapses
Areas we serve
We serve South Florida from our Florida City office, in person and by phone, WhatsApp, text and email.